
You spend decades watching taxes come out of wages. Then you retire—or you start planning for that day—and it feels like the tax problem should shrink. Sometimes it does. Often it doesn’t. Leaning on Social Security, pensions, and IRA withdrawals for your expenses will keep the IRS bill coming. A couple spending $150,000 from those sources can still land in the 22% bracket. This guide describes how those dollars are taxed, which accounts are friendlier than others, and why the order you spend from them matters—whether you have already retired or you are still drawing a paycheck and want the next chapter to be cleaner.
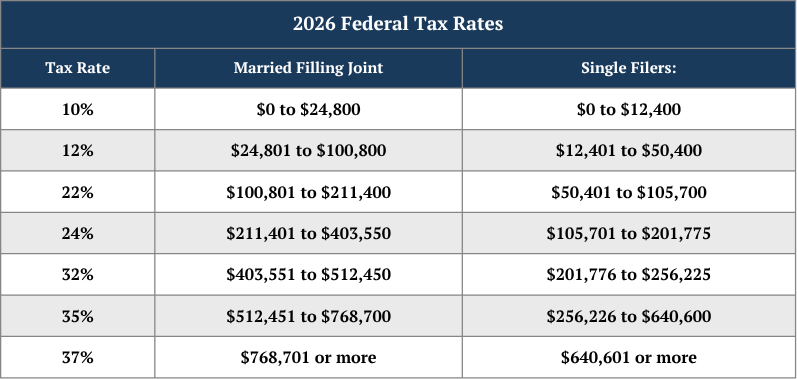
The U.S. has a progressive tax system. As income rises, the rate on the next dollar rises as well. Rates are also marginal. That means all of your income is NOT taxed at your highest rate.
Income taxes are paid on the money you earn, such as salary, wages, bonuses, & investment income. Even in retirement, many sources of income are still fully taxable. The IRS calculates your taxes based on your income level and filing status (e.g., single, married filing jointly, or head of household).
Click here to see what the income tax rate is in your state.
Think of the brackets as "buckets". You fill the 10% bucket, then the 12% bucket, then the 22%, and so on. Only the dollars that spill into the next bucket get taxed at the higher rate. The visual below helps illustrate the bucket analogy, using a married filing jointly couple:

Elite Wealth Pro Tip: Tax planning decisions such as Roth conversions, extra IRA withdrawals, and Medicare IRMAA surcharges are dependent upon the last dollar. Lifestyle planning cares about the average tax rate. Our approach to financial planning considers both.
Most common retirement income sources are taxable. This is why building up a cash reserve bucket to lean on instead of your IRA is important:

The concept of short-term & long-term gains trips people up. Here's a simple explanation. If you sell stock in a brokerage account:
One distinction that saves a lot of confusion: selling investments inside an IRA is not a capital-gains event. The tax happens when the money leaves the IRA, and it is taxed as ordinary income.
“Once I retire, I’ll be in a lower tax bracket.”
Not automatically. A retired couple spending $150,000 from Social Security, a pension, and IRA distributions will often sit in the 22% bracket. Add a large extra withdrawal—a new car, a roof, a gift to kids—and you can climb fast. Three things stack:
The paycheck went away. The tax system did not get simpler.
Everyone looks for ways to shrink taxable income, but you don’t need a 40-page tax manual. Generally, only a few items move the needle:
Deductions are the main tool to reduce your taxable income. You either take the standard deduction or you itemize—not both. For 2026, the standard deduction is $16,100 (single) or $32,200 (married filing jointly).
When to Itemize: only if mortgage interest, charity, medical costs, and other itemized expenses add up to more than the standard deduction. Example: A couple earns $410,000. The standard deduction cuts taxable income to $377,800. Itemizing only helps if their write-offs exceed $32,200. If they are still working, 401(k) contributions come off first. Those are above-the-line: they reduce income before the standard deduction. If each spouse puts in $20,000, income falls from $410,000 to $370,000. The standard deduction then takes it to $337,800.
In Retirement -> that 401(k) lever disappears. So, some useful deductions for retirees include the standard deduction (plus some senior deductions at age 65+) and charitable gifts , which includes QCDs later on to offset taxes on RMDs.
As retirement is approaches, investors realize their 401(k)s are taxable. Suddenly, they second-guess their lifelong savings plan...."Why didn't I use a ROTH?" they wonder.
If your Roth balance is small, you’re not alone. High earners were pushed toward pre-tax 401(k)s, because the goal was to reduce taxes in high-income years. Furthermore, Roth IRA contributions have income limits, which made Roth challenging as income grew. For 2026, a full contribution requires MAGI under $153,000 (single) or $242,000 (married filing jointly).
So, the typical client we see has:
Don't stress- this mix is workable. It is also why the years after work—and before RMDs—matter. You still have some control over which dollars you turn into taxable income.
Elite Wealth Pro Tip: You cannot convert your way out of a huge IRA in one year. You can convert a slice each year to fill lower tax brackets on purpose. That is a planning decision, not a December scramble.
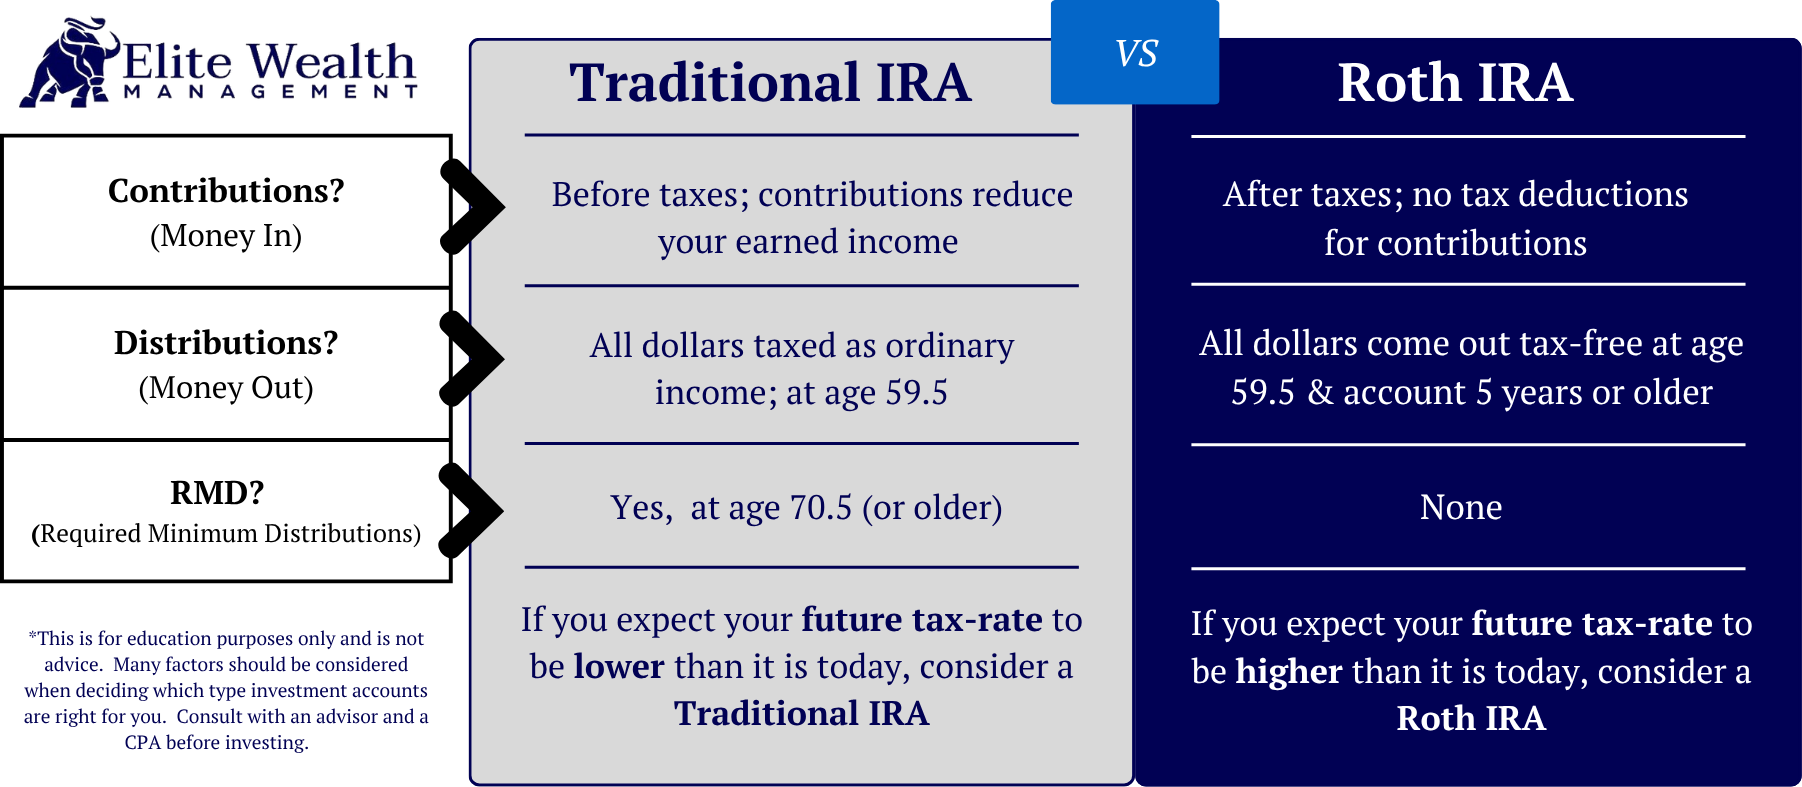
There is no universal order that fits every household. This is a starting framework, not a commandment:
Exceptions are common. A year with big medical bills, a conversion plan, a concentrated stock position, or a surviving spouse who will file single can flip the order. Estate planning belongs in this conversation too. Leaving a large traditional IRA to heirs can hand them a tax bill. That does not mean “drain the IRA tomorrow.” It means the withdrawal plan and the estate plan should talk to each other.
Given the complexity of the U.S. tax system, there are lot of myths surrounding taxes. Here are a few that I commonly come across during client conversations:
" I'm in the 24% bracket, so everything is taxed at 24%." Only the portion of your income that falls into each bracket is taxed at that rate—most of your earnings are taxed at lower rates than your highest bracket.
"IRA sales are taxed as capital gains." Stock sales inside the IRA are not taxable. Withdrawals are ordinary income.
"Retirement means lower taxes." Not necessarily...retirement income from sources like pensions, SS, or IRA distributions can push you into higher brackets, depending upon how much you liquidate.
A retirement tax plan is not a slogan. It is a map of three buckets—taxable, tax-deferred, tax-free—plus a decision about how much income you choose to recognize this year. Get those pieces on one page and the next questions get easier: When do we take Social Security? How much can we convert? How much risk should we take? Can the portfolio fund the life we actually want? That’s the work of a plan, not a tax article.
Important Disclaimer: The information provided in this guide is for educational purposes only. All examples used are based upon fictitious clients that resemble our typical clients. Nothing here within should be considered investment or tax advice. Please consult with a financial advisor and/or CPA when considering investment and tax decisions.

We generally serve families with $500k or more in retirement/investment assets. Our clients are seeking a trusted advisor to oversee investment decisions and retirement planning. Schedule a meeting to explore our services:
Schedule a Call
